Strategies
Flyagonal
The source strategy and the Optionist variant are deliberately separated here.
Original
1. Original strategy
The original setup consists of a call broken wing butterfly above price and a put diagonal below price.
Typical mechanics use short legs around 8 to 10 DTE and a longer leg with roughly double the duration.
According to the source, the profit target is roughly 10 percent of max loss, and the typical hold time is only about 3 to 5 days.
Original: call butterfly + put diagonal
- Long Call ATM −20 / 10 DTE
- 2× Short Call ATM / 10 DTE
- Long Call ATM +100 / 10 DTE
- Short Put ATM −100 / 10 DTE
- Long Put ATM −120 / 20 DTE
Optionist
2. Optionist variant
The center uses 2 short calls around delta 50, plus a long call at ATM minus 6, a long call at ATM plus 5, and a short put at ATM minus 12.
Suitable underlyings are mainly SPY, SPX, and XSP. The setup is better suited to a more volatile market with elevated IV, roughly from a VIX above 20.
SPY setup
- Long 1x call ATM-6
- Short 2x calls delta 50 / roughly ATM
- Long 1x call ATM+5
- Short 1x put ATM-12
P/L Diagram
Optionist variant
SPY: Optionist variant
- Short Put ATM −12
- Long Call ATM −6
- 2× Short Call ATM
- Long Call ATM +5
The short put drives the left tail, the profit center sits around the two short calls, and the upper call wing leaves a small residual value on the right.
Backtests
Optionist variant
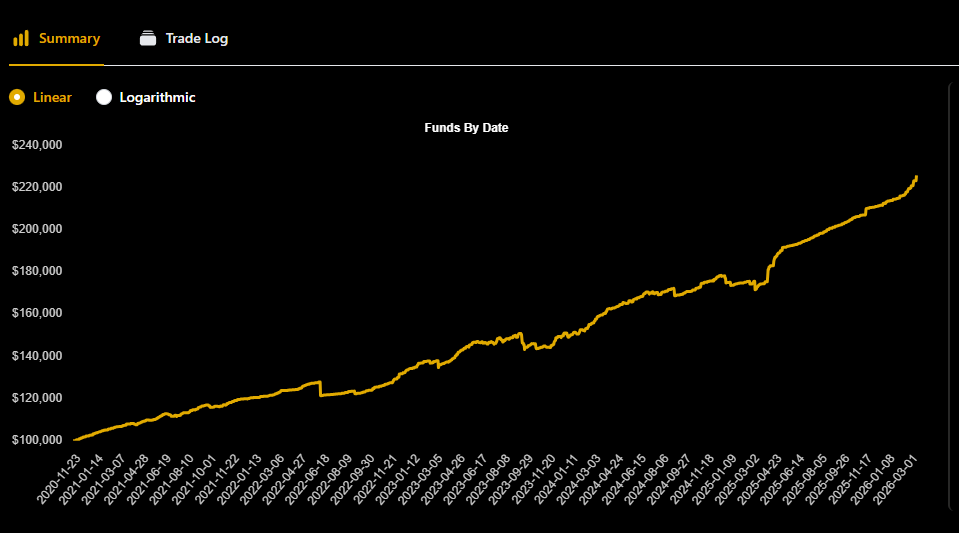
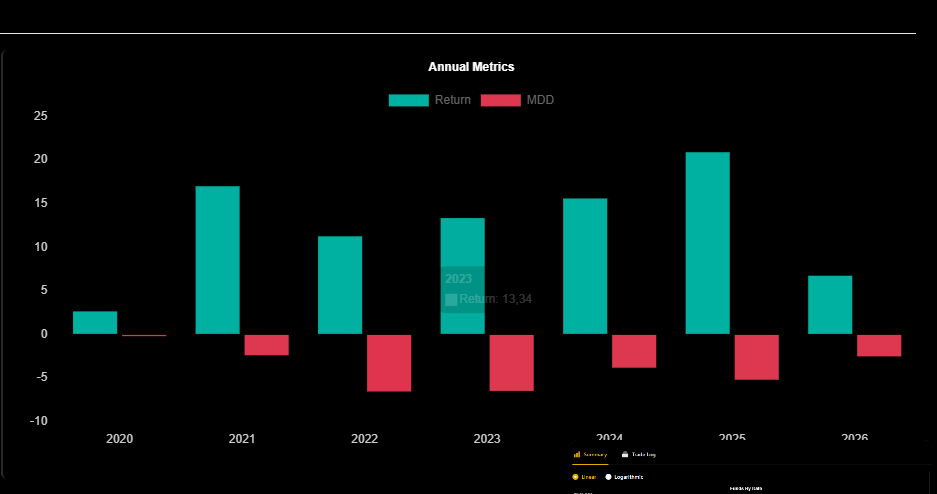
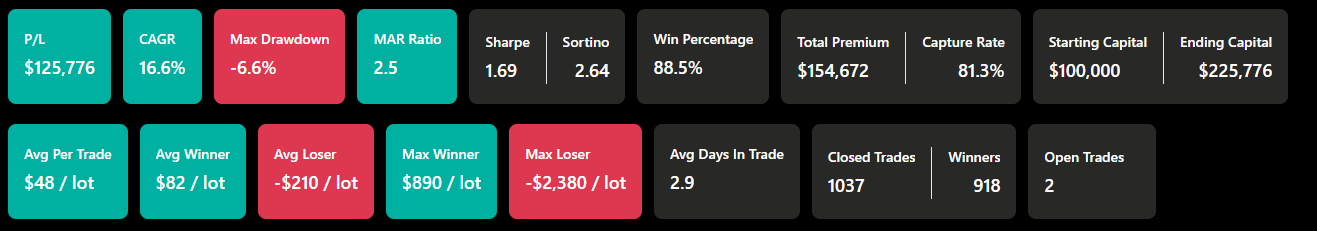
The Option Omega evaluations show the overall curve, year-by-year results, and outcome distribution.