Comparison
Original Flyagonal Strategy
The original structure is a hybrid of a call broken wing butterfly and a put diagonal.
1. Original strategy from Theta Profits
The original Flyagonal is much closer to a combination of a call broken wing butterfly above the current price and a put diagonal below the current price.
That is exactly what creates the hybrid character. The call side tends to work in calmer or moderately rising conditions through theta and often lower implied volatility, while the put diagonal can help if the market weakens and volatility expands.
- Building block 1 Call broken wing butterfly above the current price.
- Building block 2 Put diagonal below the current price.
- Short leg Often around 8 to 10 DTE.
- Long leg Usually around double the duration, roughly 16 to 20 DTE.
- Starting point Shorts placed roughly 3 percent away from the current price.
- Profit target Roughly around 10 percent of maximum loss.
- Hold time Typically about 3 to 5 days.
- Character Defined risk, positive theta, and a different vega profile than a simple butterfly.
- Management More active by design, not meant as a hold-to-expiration trade.
Original: call butterfly + put diagonal
- Long Call ATM −20 / 10 DTE
- 2× Short Call ATM / 10 DTE
- Long Call ATM +100 / 10 DTE
- Short Put ATM −100 / 10 DTE
- Long Put ATM −120 / 20 DTE
Put simply, the original Flyagonal is more of a hybrid income-and-volatility strategy with a broader, tent-like profitability zone.
Original source: Theta Profits, Flyagonal.
2. Optionist variant
The Optionist variant is much more directional and asymmetric. The core consists of 2 short calls around delta 50, plus a long call at ATM minus 6 points, a long call at ATM plus 5 points, and a short put at ATM minus 12 points.
That means the left side is no longer a clean bounded butterfly. Instead, it adds financing and directional exposure that benefits from SPY staying above the put strike. The collected credit therefore has to compensate for the open left tail, otherwise the structure is mostly naked downside risk.
The most suitable underlyings are SPY, SPX, and XSP, because they provide the liquidity needed for this kind of asymmetric build. The setup is mainly intended for a more volatile market, roughly with a VIX above 20, so there is enough premium to finance the wings.
SPY example structure
- Long 1x call ATM minus 6 points
- Short 2x calls delta 50 / roughly ATM
- Long 1x call ATM plus 5 points
- Short 1x put ATM minus 12 points
SPY: Optionist variant
- Short Put ATM −12
- Long Call ATM −6
- 2× Short Call ATM
- Long Call ATM +5
This profile shows the open downside from the short put, the highest-value zone around the two short calls, and a small positive residual shelf on the right because the upper call wing sits at ATM plus 5.
Backtest results of the Optionist variant
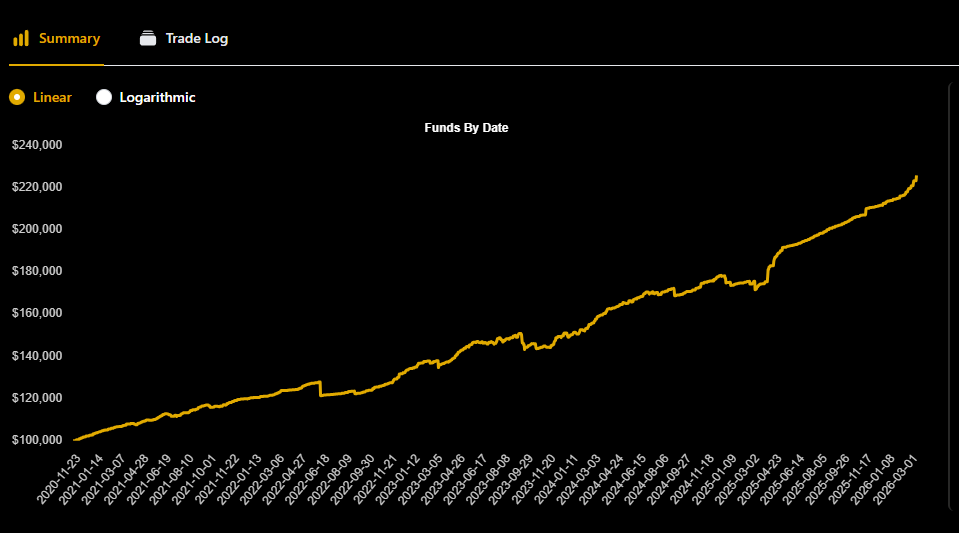
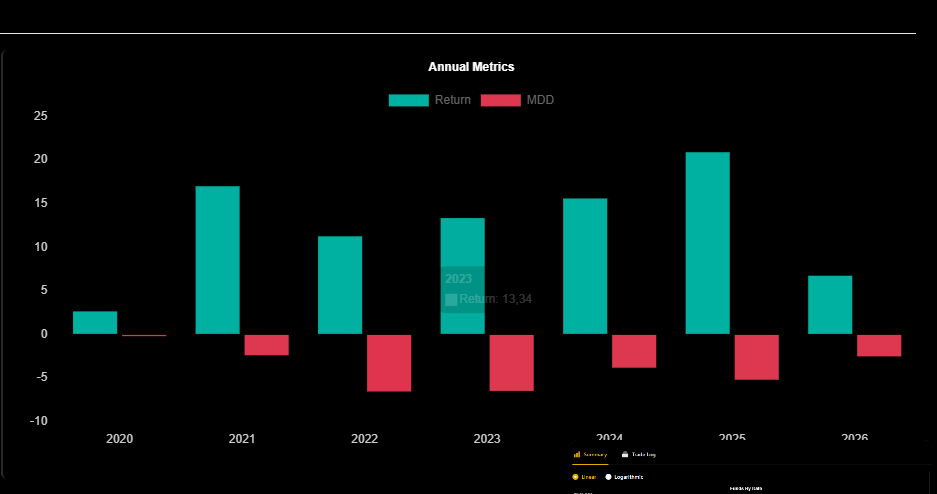
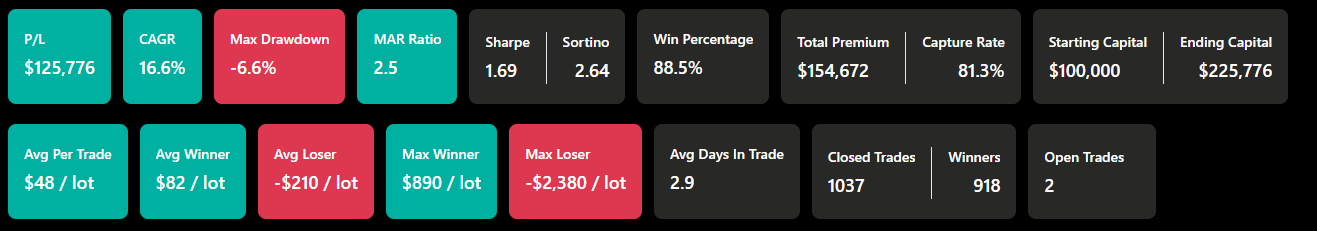
The current Option Omega evaluations of the flyagonal variant are embedded here. They show the overall equity curve, the year-by-year results, and the outcome distribution.